Texas Prompt Payment Act & 3rd Party Claims:
How Collision Centers Protect Cash Flow
Texas collision centers can bypass third-party insurance delays without relying on Texas Chapter 542. NextDay Capital Network provides $10k to $2M in unsecured working capital based on monthly revenue. Secure your Texas Prompt Payment Act collision funding in 24 hours.
Operating an independent auto body shop or collision center in Texas requires balancing shop capacity with cash flow management. When customer repairs enter your bays, speed and turnaround time determine your profitability. However, shop owners frequently run into a massive financial wall when dealing with third-party liability insurance claims.
Many Texas repair center operators assume that state legislation protects their cash flow against payment delays. Specifically, owners look to the Texas Prompt Payment of Claims Act (Texas Insurance Code Chapter 542). Understanding the legal boundaries of this statute—and securing flexible alternative capital—is critical to preventing insurance carriers from holding your working capital hostage.
1. The Texas Chapter 542 Misconception: 3rd-Party Liability Limits
The Texas Prompt Payment of Claims Act (Chapter 542) sets strict statutory deadlines for insurance companies to acknowledge, investigate, accept, or reject first-party claims. Under first-party coverage (when your direct customer files through their own policy), insurers face strict payout windows and mandatory legal penalties for statutory delays.
The trap occurs with third-party liability claims. When your customer is hit by another driver and files a claim against the at-fault driver's insurance carrier, Chapter 542 does not apply in the same mandatory manner. Third-party insurers only hold a general duty to attempt a fair settlement. As a result, carriers routinely stall claims while investigating fault, conducting lengthy administrative reviews, or disputing coverage with the other driver's policy provider.
2. Stop Acting as a Free Bank for Multi-Billion-Dollar Insurers
While two corporate insurance legal teams argue over percentage liability, your repair shop bears the entire financial burden:
Parts Invoices: OEM body panels, frame components, and sensor arrays must be paid for under strict vendor terms (often Net-30).
Technician Payroll: Master technicians and frame specialists require regular weekly payroll, regardless of claim settlement status.
Real Estate Deadlock: A repaired vehicle occupying physical floor space while awaiting third-party payout turns your repair bay into a zero-revenue storage slot.
When you use your primary business account to float these repairs out-of-pocket, you act as an interest-free lender to multi-billion-dollar insurance carriers.
3. Protecting Shop Liquidity with Unsecured Working Capital
You cannot force an out-of-state third-party insurance adjuster to speed up their administrative timeline. However, you can protect your shop's daily operational cash flow.
Top-performing Texas collision centers utilize unsecured, revenue-based working capital to decouple their operating budgets from insurance settlement cycles. By securing fast bridge capital, shop owners can:
1. Cover wholesale OEM parts invoices immediately to maintain supplier discounts.
2. Meet weekly technician payroll without dipping into emergency cash reserves.
4. Expand shop capacity and purchase modern diagnostic calibration equipment without waiting on insurance checks.
4. The Next Day Capital Network Advantage: One Application, Top 20 Lenders
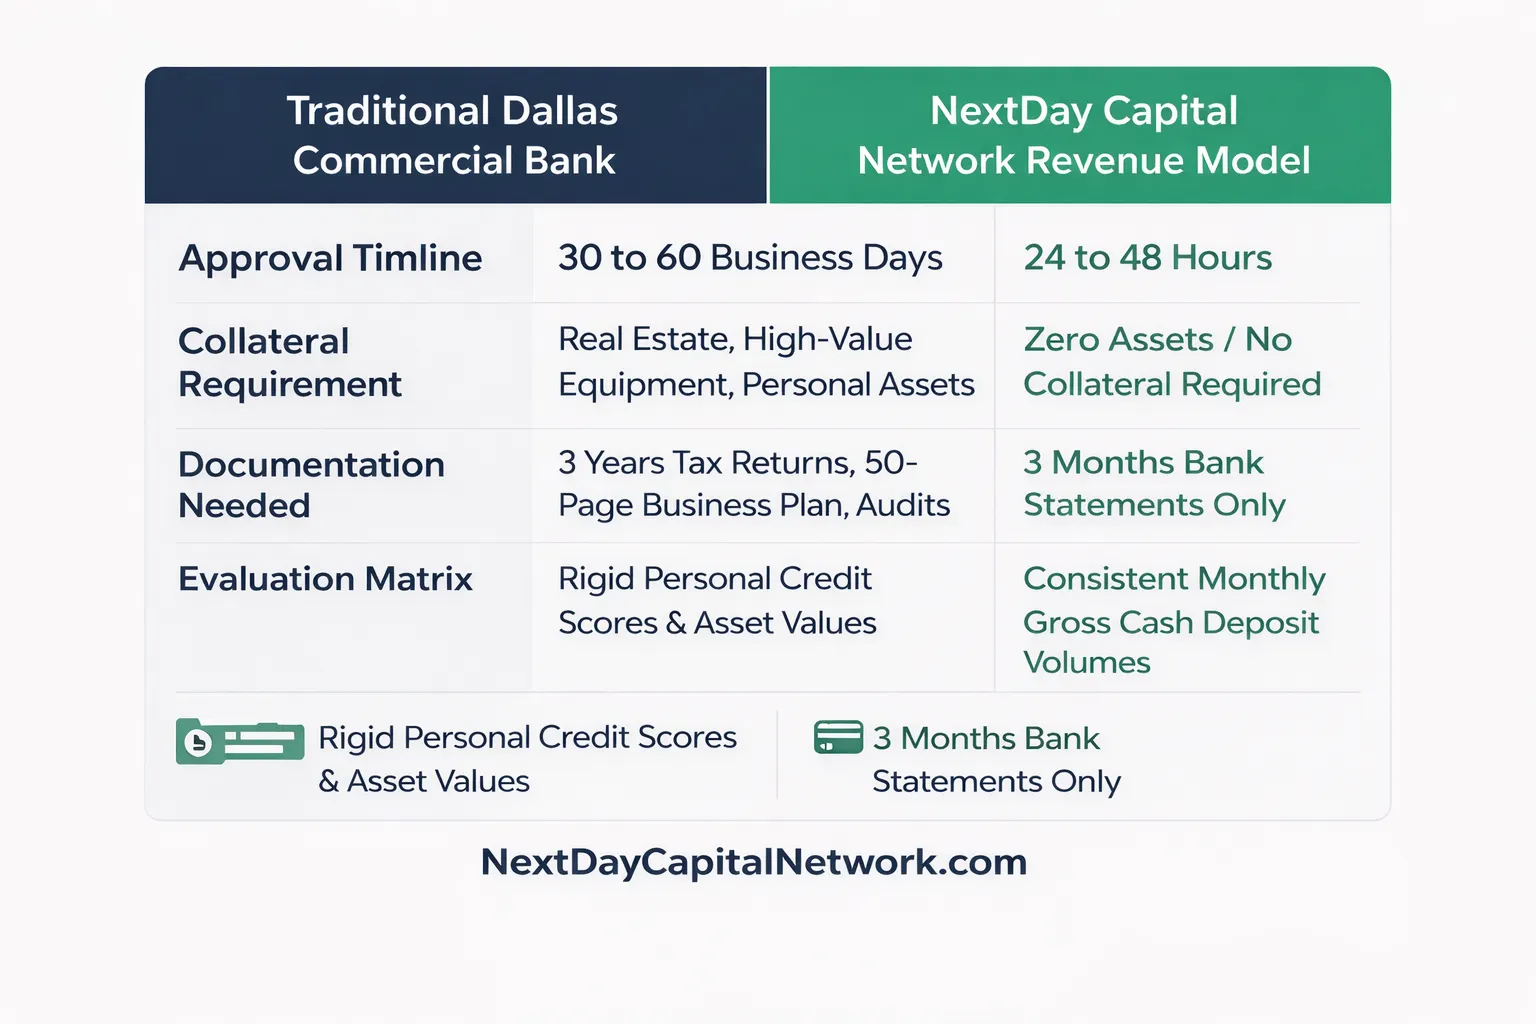
Qualifications are tailored around your actual monthly revenue flow: Traditional commercial banks fail independent auto body shops by requiring real estate collateral, 60-day approval cycles, and years of audited tax returns.NextDay Capital Network eliminates this banking friction. Our specialized platform handles the heavy lifting: with just one 5-minute application, your repair shop is placed directly in front of the top 20 commercial lenders competing to provide you with the best rates and terms.
Qualifications are tailored around your actual monthly revenue flow
🚀 Reclaim Control of Your Texas Collision Center
Stop letting third-party insurance delays dictate your shop's growth and payroll safety. Check your working capital eligibility today with zero impact on your personal credit score.
Traditional banks do not understand the collision industry. We Do...
You need a partner built for speed.
At Next Day Capital Network, we bridge the cash-flow gap with $10,000 to $2M in working capital.
We do not ask for real estate collateral.
We do not demand a business plan.
We look at your actual revenue.
If you are doing at least $15,000 a month in gross deposits and have been open for four months, you are exactly who we fund.
Approvals in hours.
Funds in your account in 24 to 48 hours.
Zero impact on your credit score to heck.